All Categories
Featured

How Professional Relocation Logistics Benefit Your 2026 Move
Table of Contents
The home buying procedure takes 45 to 90 days from accepted offer to closing, but novice home buyers in 2025 to 2026 face a 10% average down payment, the highest since 1989. With rates around 6.22% and typical home costs at $415,200, getting preapproved early and understanding your complete cost image is more important than it's remained in years.
The 2026 real estate market looks dramatically different from what we saw in 2020-2021, and even substantially different from the challenging environment of 2023-2024. According to the National Association of REALTORS, the median existing home rate sat at $415,200 as of October 2025, representing a 2.1 percent boost year-over-year.
Mortgage rates inform an encouraging story too after peaking above 7 percent in late 2023, rates have settled around 6.22 percent for 30-year set home loans since December 2025, according to Freddie Mac. Think of it like this: you're getting in a market that's discovering its balance after years of chaos. Stock is slowly improving, with 4.4 months of supply available across the country.
The real estate lack that's pestered the market for many years is gradually relieving. NAR jobs housing starts will reach 1.45 million units in the next couple years, approaching the historic average of 1.5 million yearly. More homes striking the market implies more options for you as a buyer. This is what it suggests for you: 2026 is a good time for buyers who are all set.
The Ultimate 2026 Property Buying Checklist
How well you get prepared before you start shopping is the only thing that matters in this market. I know the concept of purchasing a home feels overwhelming, specifically when you're looking at typical prices over $400,000 in lots of markets.
If your water heating unit breaks down at 2 AM or your HVAC system breaks down throughout a heat wave, you need to repair it and pay for it. Industry data states that you should reserve 1% to 3% of your home's value each year for repair work and upkeep. Let's resolve the actual numbers.
If you have to spend $4,500 a month on needs, you require to have $13,500 to $27,000 in cash. This isn't your deposit money; it's your safeguard. A steady job and income history. The majority of loan providers desire to see at least two years of constant work history, but there are some exceptions for recent graduates or individuals who are changing professions and can demonstrate how their income has changed in time.
Your overall regular monthly debt payments (consisting of the projected home loan) shouldn't go beyond 43 percent of your gross monthly earnings for traditional financing, though some programs permit up to half with compensating factors. Credit report of a minimum of 620 for traditional loans, though FHA loans might accept scores as low as 580 with 3.5 percent down or 500 with 10 percent down.
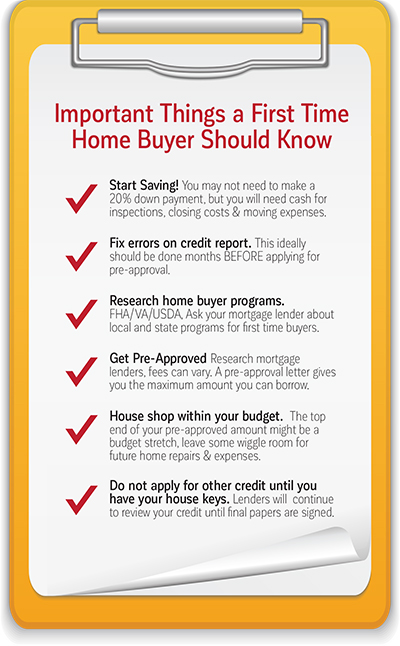
Let's put this in point of view with real numbers. If you're targeting a $350,000 home with 5 percent down: Closing expenses (approximated 3 percent): $10,500 Emergency situation fund (4 months): $18,000 Total cash required: $46,000 That's a substantial savings objective that takes most purchasers 2 to 4 years of focused effort to build up.
Modern Design Styles to Watch in 2026Complete Move-in Task List for 2026
When we acquired the group procedures I deal with now, I discovered something crucial: timing matters as much as cash. Homeownership makes many sense when you're preparing to sit tight for at least 3 to 5 years. The deal costs of buying and selling (typically 8 to 10 percent of the home's worth when you consist of both sides) mean you need time for gratitude to balance out those costs.
These are record-high numbers showing how expensive and disruptive moving has ended up being. Ask yourself these questions: Is my job steady and most likely to keep me in this location for a number of years? Am I preparing major life changes (marital relationship, kids, career shifts) that might modify my real estate requirements? Do I comprehend the complete cost of homeownership beyond just the home loan payment? Am I mentally and almost all set for the duties of home maintenance? If you're responding to no to numerous concerns, you might gain from waiting and continuing to save while clarifying your long-lasting strategies.

Latest Posts
Advanced Relocation Tactics for Success
Optimizing Your Moving Logistics in 2026

Smart Tips to Ready a Property for Sale